US federal debt just crossed $40 trillion. In Trump’s second term, the country’s already added almost $4 trillion more. The 2026 deficit is on track for $1.9 trillion. And Bitcoin — the asset that was supposed to price all of that in — is trading around $80,000, roughly 37% below last year’s record high.
That’s the problem I dug into for the BeIn Finance video below. If rising government debt and a weaker dollar are supposed to push money into scarce assets, why has Bitcoin spent most of 2026 falling? This post is the written-out version of the same argument, with the sources and the trader takeaways I couldn’t fit into the video.
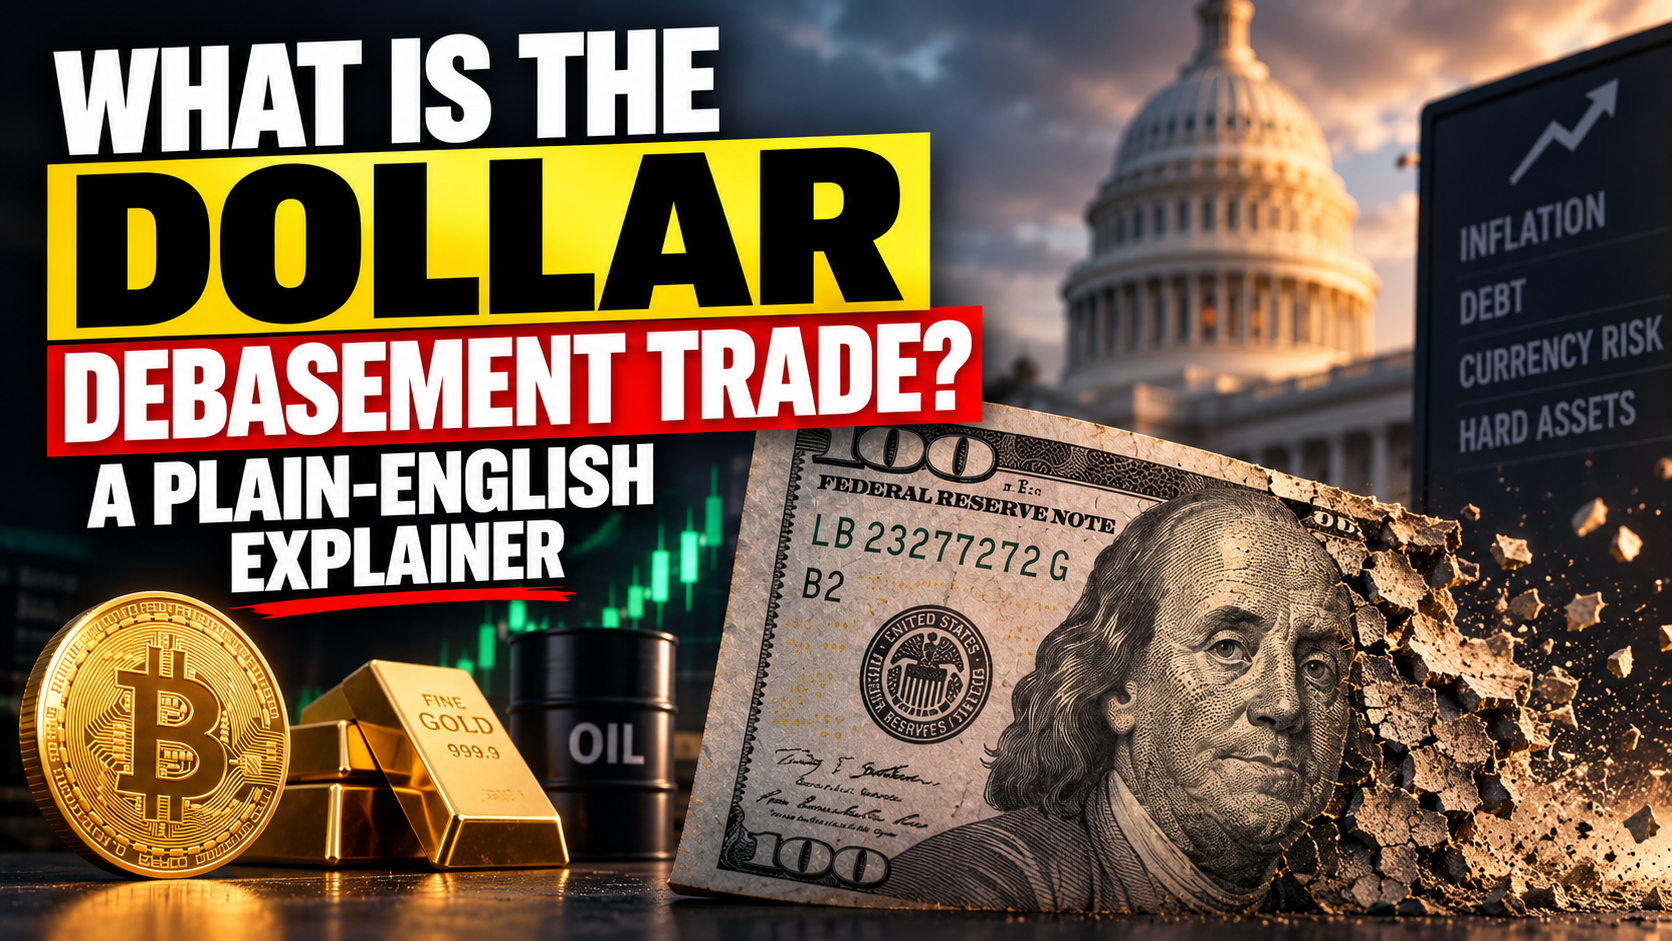
Short answer: The dollar (or Bitcoin) debasement trade is the thesis that governments running massive deficits eventually push central banks toward easy money — so investors get ahead of it by buying scarce assets like gold and Bitcoin. The thesis worked from 2020–2024. It broke in early 2026 after Kevin Warsh’s nomination to run the Fed signalled that the central bank would tolerate high rates rather than absorb fiscal pressure. Then in August 2026, the Treasury doubled its bond buyback capacity, Bitcoin rallied 26% in a month, and the debate reopened. The trade isn’t dead — it’s morphing into a bet on financial repression instead.
Last verified: September 2026. Source: BeInCrypto’s US debt debasement trade coverage.
Key takeaways
- The debasement trade rests on expectations of policy response, not on the size of the deficit itself.
- Kevin Warsh’s Fed nomination broke the thesis in early 2026 because markets stopped expecting balance-sheet expansion.
- The August 2026 Treasury buyback expansion ($2B → $4B per operation) reopened the trade as an implicit yield cap.
- The 1942–1951 Fed yield cap at 2.5% is the historical precedent for how far a government can go to protect its own debt.
- Bitcoin’s 2026 weakness is a mix of halving-cycle timing (peaked ~534 days post-halving) AND the broken macro thesis.
What is the dollar debasement trade?
The debasement trade is the market strategy of buying scarce assets — gold, silver, Bitcoin — in anticipation of currency devaluation driven by government debt and central bank easing.
The logic runs like this:
- Governments run enormous, persistent deficits.
- Eventually, borrowing costs become unsustainable.
- Central banks step in to keep rates low — through rate cuts, QE, or direct bond buying.
- This expands the money supply relative to real-world goods and scarce assets.
- The value of the currency erodes.
- Investors who moved into scarce, non-printable assets ahead of this get “carried” through the devaluation.
Gold has done this for 5,000 years. Bitcoin has been the digital-age version of the same trade since roughly 2020, when the pandemic-era money printing sent both assets to record highs.
The critical insight most people miss: the debasement trade isn’t about the deficit. It’s about what investors expect policymakers to do about the deficit. Take away the expectation of easy money and the scarce-asset premium collapses even while the debt keeps piling up.
For the wider Bitcoin macro framework, crypto market cycle, bitcoin dominance, and what is the Japanese yen carry trade are the three companion posts worth reading alongside this one.
What is the Bitcoin debasement trade specifically?
Bitcoin fits the debasement trade template better than any other asset in modern history.
Why it works in theory:
– Fixed supply cap — 21 million BTC, ever. Programmed in.
– Halving schedule — new issuance cuts in half roughly every four years. See bitcoin halving explained.
– Global, borderless — no jurisdiction can print more of it.
– Digital gold parallel — the “store of value” narrative maps directly onto the debasement thesis.
– Liquid and tradeable — unlike physical gold, you can trade Bitcoin from your phone at 3am on a Sunday via any major exchange, including BitGet.
Why it also gets pulled around by macro:
– Institutional holders treat BTC as a risk asset first, digital gold second.
– BTC’s volatility is 4–6× higher than gold’s — so macro shocks hit it 4–6× harder.
– Bitcoin correlates with tech stocks and other high-beta risk assets more than it correlates with gold in short windows.
That last point is the crux. When the debasement trade works, Bitcoin behaves like digital gold and outperforms. When macro flips risk-off (like the yen carry trade unwind in August 2024), Bitcoin behaves like a leveraged tech stock and sells off harder than any other asset.
Why has the debasement trade broken down in 2026?
Three reasons the thesis stalled through the first half of 2026.
1. The Kevin Warsh nomination changed expectations
Kevin Warsh was nominated to run the Federal Reserve, and markets read him as fundamentally different from his predecessors. Warsh is broadly seen as more hawkish — less willing to expand the Fed’s balance sheet, more willing to let long-term rates absorb fiscal pressure. Per BeInCrypto’s Warsh coverage, his first Fed meeting killed the market’s assumption that cheap money returns in 2026, and futures traders repriced hike odds to 66% before year-end.
That single expectation shift did what four trillion dollars in new debt couldn’t do — it broke the debasement narrative.
2. Real yields stayed high
The 10-year real Treasury yield — the return you get after inflation is stripped out — sat around 2.4% for most of 2026. That’s a strong real return.
When you can earn 2.4% real yield on a US Treasury bond with no volatility and no drawdown, a chunk of the money that might otherwise chase Bitcoin has a comfortable, boring place to sit. The opportunity cost of holding Bitcoin (which pays zero yield and is 60% off its highs) becomes real.
3. The 4-year cycle timing is what it is
Bitcoin’s price action in 2026 followed the same rhythm as 2017 and 2021. It peaked roughly 534 days after the April 2024 halving, then fell more than half from the top. Nothing about that requires a macro thesis — it’s just the 4-year cycle doing what it always does.
So how much of 2026’s Bitcoin weakness is macro vs cycle? Honestly, both. Untangling the two is why traders find this year so frustrating.
Who is Kevin Warsh and why does it matter for Bitcoin?
Kevin Warsh is the current Fed Chair (as of writing) and — per BeInCrypto’s profile piece — the reason the debasement thesis got repriced this year.
Three things to know about him:
One. He served on the Fed board during the 2008 financial crisis and has publicly criticised the Fed’s post-crisis expansion of its balance sheet. He thinks the Fed got too big, too politically involved, and too willing to bail out fiscal profligacy.
Two. His public writings favour rules-based monetary policy — meaning the Fed should stick to inflation targeting and not respond to bond market panics by cutting rates. That’s the opposite of what the debasement trade needs.
Three. His first Fed meeting dropped the dot plot’s last remaining rate cut projection for 2026, and hike odds jumped to 66%. Markets took his signal seriously.
For a Bitcoin trader, Warsh’s Fed is the worst monetary backdrop possible for the debasement thesis. He’s the human-shaped roadblock to easy money. As long as he’s in the seat, the trade is fighting policy uphill.
What happened in August 2026 that changed everything?
Two events in mid-August reopened the debasement thesis after months on ice.
The 30-year yield spike
On 18 August 2026, the 30-year Treasury yield hit its highest level since 2007. The yield on the government’s longest-dated debt is essentially the price the market charges for lending to the US for 30 years — and it just hit an 18-year high.
For a government carrying $40T in debt and running $1.9T annual deficits, higher long yields are a genuine emergency. Every additional basis point on the 30-year adds real money to future interest payments.
The Treasury buyback expansion
One day later, on 19 August, the US Treasury doubled its liquidity support for buying 10- to 30-year bonds — from $2 billion to $4 billion per operation. The timing was not accidental. When the market pushed long yields to two-decade highs, the Treasury stepped in with a mechanism designed to buy bonds and take pressure off yields.
Bitcoin rallied 26% in August, per BeInCrypto’s coverage of the debasement pivot. Gold rose 15%. The scarce-asset trade found a pulse.
But — and this is the critical point most retail traders miss — Treasury buybacks are not QE.
Are Treasury buybacks the same as quantitative easing?
No. They are mechanically different, and the difference matters.
Quantitative easing (QE): The Federal Reserve creates new money out of nothing and uses it to buy government bonds. This directly expands the money supply. It’s the tool that ran the 2020-2021 balance sheet expansion.
Treasury buybacks: The US Treasury Department uses cash it already has — tax receipts, or borrowing from elsewhere — to buy back specific bonds it doesn’t want to service anymore. It swaps around which bonds are outstanding, but it doesn’t create new money.
So on paper, buybacks are neutral. The market noticed something different, though. What matters isn’t the mechanism — it’s the signal. If investors think that every time long yields spike, the Treasury will step in with buybacks to lean against the move, they’re pricing in an implicit ceiling on borrowing costs. That’s not neutral. That’s a policy.
Economists have a name for this: financial repression.
What is financial repression?
Financial repression is the policy of keeping government borrowing costs artificially low while inflation quietly erodes the real value of the debt over time.
The government doesn’t need to formally cap yields to run financial repression. It just needs to consistently show up whenever markets try to push rates higher. Over months and years, this creates:
- Below-market yields on government debt (repressing the return savers earn).
- Above-inflation ongoing debt service in real terms (which erodes the burden without a formal default).
- A tacit expectation that the government will always protect its own debt market.
For savers and bondholders, this is a slow-motion loss of purchasing power. For scarce assets like Bitcoin and gold, this is the ideal backdrop — the exact conditions that make the debasement trade actually pay.
The August buyback expansion was arguably the first move in a financial repression regime. Whether it’s the last one is what the whole market is now watching.
What is the 1942–1951 Fed yield cap precedent?
Between 1942 and 1951, the Federal Reserve capped long-term Treasury yields at 2.5% by law to help finance the enormous debt built up during World War II. It’s the strongest historical precedent for what financial repression looks like at extreme scale.
Here’s what happened:
- The Fed was legally required to buy any Treasury bond that would otherwise trade above the 2.5% yield cap.
- This forced the Fed to absorb whatever supply the government issued.
- Inflation ran hot for years — often into double digits — because the Fed couldn’t raise rates to fight it without breaking the cap.
- Bondholders got their coupon payments in full but were quietly losing purchasing power the entire time.
Think of it less as a printing press and more as a thermostat that someone else controls. The number on the wall barely moves, but the temperature in the room certainly does — and you’re the one who has to live with it.
Bitcoin doesn’t need a repeat of the 1940s cap to benefit from this playbook. It just needs investors to believe governments are willing to protect their debt markets — whatever tool ends up doing it. If August’s buyback was the first sign, and if we see more of them through late 2026 and 2027, the debasement trade doesn’t just come back to life. It goes into overdrive.
Is Bitcoin’s 2026 weakness just the 4-year cycle?
Partly, yes. And partly, no.
The cycle argument. Bitcoin peaked around 534 days after the April 2024 halving. That timing lines up almost exactly with the 2017 and 2021 cycle peaks. Historic post-peak drawdown = 65-77%. If 2026 is running the same script, a 37% drop from the top is roughly on schedule, and the low is still ahead of us.
The macro argument. The debasement trade breaking in early 2026 added weight to what would already have been a cycle-driven correction. Bitcoin fell harder than 2017 or 2021 patterns would predict, partly because macro was fighting the technical setup.
The synthesis. Both are true. About 60% of Bitcoin’s 2026 weakness is cycle-driven — normal post-halving unwind. About 40% is macro — the Warsh Fed and the high real yield backdrop making the debasement trade fail.
The interesting question is what happens on the way up. If the debasement trade reactivates (August signals continue), the next cycle top could be substantially higher than the pure-cycle model predicts. If Warsh keeps rates high and buybacks stay small, the next cycle top could be lower than 2021’s inflation-adjusted equivalent.
For traders trying to position around this, best crypto to buy now has the framework I use, and crypto trading psychology covers why most people get this exact call wrong emotionally.
Trade around macro events on the exchange I use.
BitGet gives you spot, futures, and bots on the same account — everything you need to reposition when the macro thesis shifts.
Referral link. Not available to US residents.
What is Token 2049 Singapore and why does it matter here?
Token 2049 Singapore runs on 7–8 October 2026 and this year the institutional side of the program is arguably the whole story.
The speaker list on the institutional track reads like a who’s-who of the people who actually decide whether the debasement trade gets priced in as a policy call or dismissed as a one-off:
- Adena Friedman — CEO of NASDAQ.
- Jenny Johnson — CEO of Franklin Templeton.
- Raoul Pal — long-standing debasement-trade advocate.
- Tom Lee — the analyst who’s been calling this thesis for years.
- Senior figures from BlackRock, JPMorgan, Morgan Stanley, NYSE and CME.
Two days. Everyone who moves institutional flow. Right after Kevin Warsh’s second Fed meeting and right before end-of-Q4 positioning.
If you’re actively trading around the debasement thesis, Token 2049 is the single most concentrated source of forward guidance for the next 6 months. It’s also a signal — the fact that the institutional side is now the dominant conversation at what was historically a retail-focused crypto event tells you where the flow is coming from.
For anyone who wants to learn to read these institutional signals systematically, Trade Travel Chill (referral) is the community I’m part of. Annii’s TBD System gives you a framework for translating macro events into position-sizing decisions rather than emotional trades. Detail in trade travel chill review.
What does the debasement trade mean for Bitcoin holders right now?
Practical framework for how to think about your position.
If the debasement trade reactivates (base case):
The August buyback becomes the first of many. Warsh gets political pressure to soften. Real yields drift lower. Bitcoin recovers the cycle-model implied top and potentially overshoots. Timeline: 6–18 months.
Position: Long-term Bitcoin holdings stay on Ledger Nano X cold storage. Consider gradual DCA additions during macro-driven drawdowns via DCA bots. See how to store crypto safely for the storage architecture.
If the debasement trade stays broken (bear case):
Warsh holds the line. Real yields stay above 2%. Bitcoin trades in a wider range, 60-100k for 12–18 months. Retail attention drifts elsewhere.
Position: Same cold storage playbook. Reduce active trading position size. Take income from stablecoin yield in the meantime — see BitGet Earn or USDT vs USDC for options.
If financial repression accelerates (bull tail case):
Government caves fully. Explicit yield curve control returns. Inflation runs hot. Bitcoin trades like it did in 2020-2021 but with a larger institutional base. Timeline: variable, but tails can be extreme.
Position: Maximum long-term Bitcoin allocation you can sleep with. Consider taking profits in tranches at prior all-time-high multiples. Structural cold storage plus tax planning (Koinly or similar).
Whatever you do, don’t run this decision through Twitter. The debasement trade is a multi-quarter, multi-year thesis. It’s not a swing trade. Trying to trade it on a daily or weekly basis is how retail loses money to institutions who patiently accumulate the same thesis over years.
What should crypto traders watch for next?
Three data streams to keep on your monitor.
One. US 10-year real yield. Bloomberg or TradingView. If it breaks meaningfully below 2%, the debasement trade activates. If it holds above 2.5%, the trade stays broken.
Two. Treasury buyback size and frequency. The August operation doubled to $4B. If subsequent operations get bigger or more frequent, the market will price this as policy. If it fades to nothing, dismiss the August event as a one-off.
Three. Warsh Fed dot plot and press conferences. Every FOMC meeting matters more than it used to. Watch for hawkish-to-dovish drift in Warsh’s language. Any concession from him toward rate cuts is a massive signal.
Bonus reads: BeInCrypto’s tracker on Warsh’s Fed is the single best day-to-day source. The Congressional Budget Office publishes deficit projections quarterly.
The debasement thesis or the cycle — either way, self-custody wins.
Long-term Bitcoin sits on a Ledger Nano X. The government’s fiscal choices don’t touch your keys.
Affiliate link.
Frequently asked questions
What is the dollar debasement trade in simple terms?
The debasement trade is the strategy of buying scarce assets like gold and Bitcoin in anticipation of currency devaluation. The idea is that as governments run huge deficits and central banks eventually ease policy to protect debt markets, fiat currency loses purchasing power, so assets with fixed or capped supply become more valuable in comparison.
Why did the debasement trade break in 2026?
The nomination of Kevin Warsh as Federal Reserve Chair fundamentally changed market expectations. Warsh is viewed as a hawkish, rules-based central banker who is unlikely to expand the Fed’s balance sheet aggressively. With expectations of easy money gone, the scarce-asset premium collapsed even as US debt kept rising.
Are Treasury buybacks the same as QE?
No. Treasury buybacks use existing cash (tax receipts or new borrowing) to buy back specific bonds. They don’t create new money. QE is when the Federal Reserve creates new reserves and uses them to buy assets, directly expanding the money supply. However, buybacks can produce similar market effects if the market interprets them as an implicit yield cap.
What is financial repression?
Financial repression is a policy stance where the government keeps its own borrowing costs artificially low while inflation quietly erodes the real value of the debt over time. Savers and bondholders lose purchasing power. Scarce assets like Bitcoin and gold typically benefit as they preserve real value.
What happened in the 1940s Fed yield cap?
From 1942 to 1951, the Federal Reserve was legally required to cap long-term Treasury yields at 2.5% to help finance World War II debt. Inflation ran hot for years afterward, and bondholders lost real purchasing power. It’s the strongest historical precedent for large-scale financial repression.
Why has Bitcoin fallen in 2026 despite record US debt?
A mix of two forces. First, the debasement trade broke because markets stopped expecting easy money from Warsh’s Fed. Second, Bitcoin is running its normal 4-year cycle unwind — it peaked roughly 534 days after the April 2024 halving, in line with 2017 and 2021 patterns. Roughly 60% cycle, 40% macro.
Is Kevin Warsh bad for Bitcoin?
In the short term, yes — his hawkish stance makes the debasement trade harder to price. In the long term, his willingness to let long yields absorb fiscal pressure may accelerate the exact fiscal crisis that eventually forces financial repression. Which is bullish Bitcoin. Short-term pain, long-term thesis.
Should I sell my Bitcoin because the debasement trade broke?
Not on this argument alone. If your thesis is multi-year, macro pauses shouldn’t shake you out. If you’re actively trading, reducing size until the debasement thesis or the cycle produces a clear signal is defensible. See how to set stop losses in crypto trading for active-trader framework.
What is Token 2049 Singapore?
Token 2049 is one of the largest crypto industry conferences in the world, held annually in Singapore. The 2026 edition runs 7-8 October and includes institutional speakers from NASDAQ, Franklin Templeton, BlackRock, JPMorgan, Morgan Stanley, NYSE, and CME. It’s the biggest single event for institutional macro debate in the crypto industry.
How do I actually trade the debasement thesis?
Long-term: hold Bitcoin on cold storage, ignore short-term drawdowns. Add during macro-driven downdrafts. Active trading: watch the 10-year real yield, Treasury buyback size, and Warsh’s language. Reduce size going into major macro events. Learning to trade macro properly is one of the harder skills in crypto — Trade Travel Chill is where I structured my own learning.
Final word
The debasement trade isn’t a get-rich-quick thesis. It’s a multi-year bet on how governments respond to their own fiscal choices. It works when policy makers accept financial repression to protect debt markets. It stops working when a hawkish central banker decides to let borrowing costs rise instead.
August 2026 was the first month in a while where the trade found a heartbeat again. Whether that pulse becomes a steady beat depends on what Warsh does, what the Treasury does, and what the market prices in as policy over the next 12 months.
Either way, don’t try to time this on a weekly chart. The debasement trade unfolds on a macro timeline. Position accordingly.
Right — over to you.
Disclaimer: Crypto trading carries significant risk. You can lose all of your capital. Nothing in this article is financial advice — it’s my personal opinion and macro analysis as a retail trader. Macro commentary is educational and based on public information at time of writing. Always do your own research and consult a professional adviser where appropriate.
Affiliate disclosure: Some links in this article are affiliate or referral links. If you sign up through them I may earn a commission, at no extra cost to you. I only link to products and platforms I actually use.
Last updated: September 2026.
Alan Spicer
Crypto trader since 2020 · Coin Bureau · Crypto Banter · Trade Travel Chill
Alan has been in crypto for nearly six years. He writes what he wishes someone had told him on day one — the wins, the rugs, and the stuff the YouTubers won’t say on camera.
Related posts
- What is the Japanese Yen Carry Trade?
- Crypto Market Cycle: The 4-Year Pattern
- Bitcoin Halving Explained